

There is a moment that separates people who are trading from people who are only watching a number change, and it is not an entry. It is the first time the money leaves the platform and lands in a bank account. Which is why how to withdraw from forex trading account balances is a question worth answering carefully rather than assuming it will sort itself out later.
Most people postpone it. The balance is growing, moving money out feels like interrupting something, and there is always a reason to leave it one more month. Then, eventually, they try, and they discover that the process has requirements nobody mentioned at the deposit stage, or worse, that the platform has requirements which do not exist anywhere in financial regulation.
This article covers both: the ordinary mechanics that apply at a legitimate firm, and the pattern that tells you the money was never going to come back. It belongs under Protect, because a gain you cannot realise is not a gain, it is a screenshot.
How to Withdraw From Forex Trading Account Balances, Step by Step
At a regulated firm the process is dull, which is the correct adjective for it. Four things govern it.
Identity verification has to be complete first. Not started, complete. Firms are required to know who their customer is, and many of them will let you deposit and trade while the file is still open but will not release a penny until it closes. This is the single most common reason a first withdrawal sits in limbo, and it is entirely avoidable by finishing the paperwork on day one rather than on the day you want the money.
Money usually returns the way it arrived. If you funded by card, the first tranche generally goes back to that card, up to the amount you deposited, before any remainder can go to a bank transfer. This is an anti money laundering control rather than an inconvenience invented to annoy you, and it explains a great deal of the confusion people have about why they cannot choose their own payout method.
Only free margin can leave. The balance on the screen is not the withdrawable amount if positions are open. Margin already committed to those positions is locked, and unrealised profit is generally not available until the trade closes. Requesting more than the free margin either fails outright or, on some platforms, is accepted and then quietly reduces the cushion under your open trades, which is a worse outcome than a rejection.
Processing time and settlement time are different numbers. The firm's internal approval might take one business day. The payment rail then takes its own time, and neither clock runs at the weekend. A withdrawal requested on a Friday afternoon is not late on Monday morning.
Why the First Withdrawal Should Be Small, and Early
Here is the argument in one line of arithmetic, and it is the most useful thing in this article.
Suppose there is 10,000 of capital sitting on a platform. A test withdrawal of 50 costs 0.5 per cent of that capital in inconvenience and possibly a fee, and it tests 100 per cent of it. That is a ratio of 200 to 1 between what is being verified and what is being spent to verify it. Make the test 100 and the ratio is still 100 to 1.
No other due diligence you can perform comes close to that. Reading the licence number, checking the regulator's register, reading reviews, all of it is worth doing and none of it produces the same evidence as money actually arriving in your bank account with your name on it. A platform either pays or it does not, and the cheapest possible way to find out is to ask it for a small amount early, before the balance is worth anything.
Do it in the first fortnight. Do it before the account is large enough for the answer to matter emotionally. The single worst time to discover a withdrawal problem is the first time you have a meaningful sum at stake.
The Ordinary Reasons a Legitimate Withdrawal Is Delayed
Delays are common and mostly boring. Five causes account for the large majority of them.
- A name mismatch. The bank account, the card and the trading account must all carry the same name. Withdrawals to a spouse, a parent or a company account are refused as a matter of policy almost everywhere.
- Incomplete verification. Documents expired, address proof older than the firm's window, a photograph where a corner of the document is cut off.
- Bonus or credit terms. If a deposit bonus was accepted, there is usually a volume condition attached before funds become withdrawable. This is a good reason to decline bonuses entirely.
- Insufficient free margin, as above.
- Banking calendars. Public holidays in the firm's jurisdiction, in the payment processor's jurisdiction, and in yours, none of which line up.
What all five have in common is that the firm tells you which one applies and the problem has a fix. That is the distinguishing feature. A real delay comes with a specific, checkable reason.
When a Blocked Withdrawal Is Not a Delay at All
There is a different pattern, and it has a documented shape worth recognising before it happens to you rather than afterwards.
The FBI's Internet Crime Complaint Center describes it directly in its 2025 annual report. Victims are approached on social media or messaging apps, introduced to investment groups presenting themselves as knowledgeable insiders offering guidance on trading cryptocurrency or gold, and shown fake profits on a platform that looks entirely normal. The report's own words for what happens next are the part to remember: eventually, when the victims try to withdraw their money, they will be charged taxes and fees as a final attempt to exploit money from the victims before the scammers disappear with all the victim funds.
Read that sequence again, because it inverts the usual intuition. The withdrawal request is not the moment the fraud is discovered. It is the moment the fraud enters its most profitable phase. The demand for a tax payment, a release fee, an insurance deposit or a conversion charge before funds can be sent is not a bureaucratic obstacle standing between you and your money. It is the product.
The same report notes that victims are then targeted again by recovery scams promising to retrieve the lost funds, which is worth knowing in advance because it is the cruellest part of the cycle and it catches people at their most desperate.
The rule that follows is simple and has no exceptions worth entertaining: a legitimate firm never requires a new payment in order to release your own money. Fees are deducted from the amount being sent. They are never collected separately in advance. If someone is asking you to send money in order to receive money, the conversation is over.
The Withdrawal Policy, and What It Is Actually Worth
Mechanics aside, the more interesting question is how much should leave and how often. Most people answer it by feel, which means they answer it never.
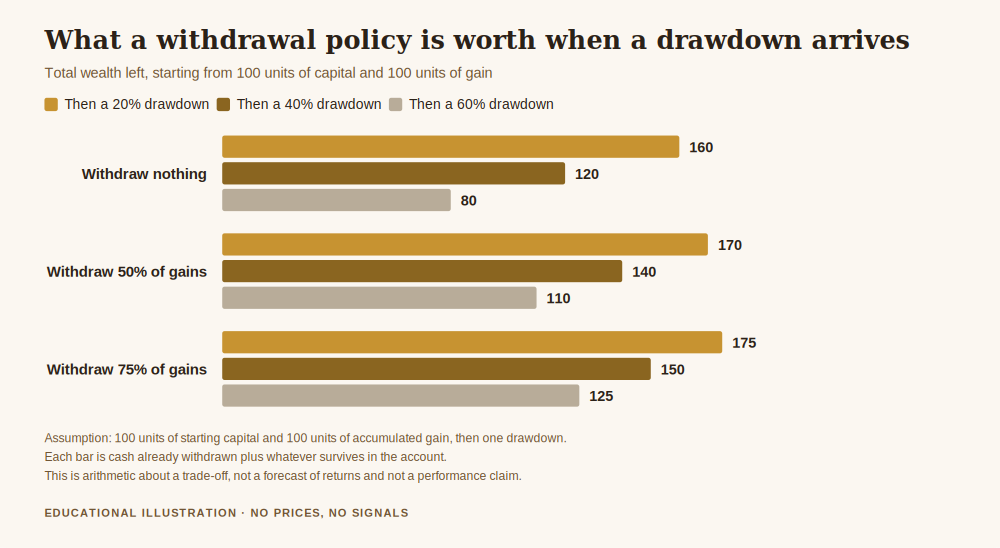
The trade-off is real and it is worth seeing in numbers rather than arguing about in the abstract. Take 100 units of starting capital and 100 units of accumulated gain, so the account stands at 200. Now a drawdown arrives, because drawdowns arrive. Count total wealth as cash already withdrawn plus whatever survives in the account:
- Withdraw nothing: after a 20 per cent drawdown you hold 160, after 40 per cent you hold 120, after 60 per cent you hold 80.
- Withdraw half the gains: the same three drawdowns leave you with 170, 140 and 110.
- Withdraw three quarters of the gains: 175, 150 and 125.
The pattern is the point. The harder the drawdown, the more the withdrawal policy is worth. At a 20 per cent drawdown, taking three quarters out rather than nothing is worth 15 units. At a 60 per cent drawdown it is worth 45 units, three times as much. Withdrawals are cheap insurance in good conditions and extremely valuable in bad ones, which is precisely the property you want and precisely the property that makes them feel unnecessary at the moment of decision.
The cost is equally real and should be stated plainly: money withdrawn is money no longer compounding. Nobody can tell you the right split, because it depends on what the capital is for and what else you have. What can be said is that a policy decided in advance and written down will beat an improvised decision taken during either euphoria or panic, and that is true of nearly every rule in this business.
One regulatory note belongs here. The European measures of 27 March 2018 introduced negative balance protection on a per account basis alongside a margin close out rule standardised at 50 per cent of minimum required margin. The first means a retail client in that regime cannot end up owing more than the account held. The second means positions are closed for you before the account reaches zero. Neither is a substitute for taking money out, and neither applies universally, because rules differ by jurisdiction and by the entity your account is actually held with. That last detail is worth checking, since large firms operate several entities under different regulators.
Get the free Black Gold Market blueprint, a short document on protecting capital before you try to grow it, including the withdrawal arithmetic used on this page. One email, no spam, unsubscribe anytime.
Get the free blueprint →Frequently Asked Questions
How to withdraw from forex trading account balances without closing my positions?
Withdraw only from free margin, which is the balance not committed to open trades. Check the free margin figure rather than the balance figure before requesting, and leave a meaningful buffer above the minimum, because taking the cushion down to nothing means an ordinary adverse move now triggers a close out that would not otherwise have happened.
How long should a withdrawal take?
Internal approval at a regulated firm is typically within one to a few business days, then the payment rail adds its own time depending on the method. The number that matters is not the average but whether the firm gives you a specific status and a specific reason when something stalls.
Is a withdrawal fee normal?
A fee deducted from the amount sent is normal and is disclosed in the firm's terms. A fee you are asked to pay in separately, before the withdrawal can be released, is not normal under any circumstances and is the pattern described in the IC3 report above.
Should I withdraw profits monthly or let them compound?
That is a personal decision about what the capital is for, and this article deliberately does not answer it. What it does say is that the decision should be written down in advance as a rule, and that the arithmetic above shows the value of any withdrawal policy rises sharply with the size of the drawdown it eventually meets.
What should I do if a withdrawal is refused without a clear reason?
Stop depositing immediately, request the reason in writing, and check the firm's registration with the regulator it claims to be authorised by. Do not send any further payment of any kind, including anything described as a tax, release fee or verification deposit.
Where did the numbers in this article come from?
The withdrawal fraud pattern and the recovery scam note are quoted from the FBI IC3 2025 annual report linked above, checked live before publication. Negative balance protection and the 50 per cent margin close out rule are quoted from the ESMA measures of 27 March 2018, also linked and checked. The test withdrawal ratios are the capital divided by the test amount. The drawdown table is cash withdrawn plus the remaining balance multiplied by one minus the drawdown, starting from 100 units of capital and 100 units of gain. None of it is a forecast, and the 100 units of gain is an assumption for the arithmetic rather than a claim that such a gain is available.
Where Black Gold Market Fits
Black Gold Market is free to follow. Daily XAU/USD analysis with the level, the context and the risk stated before the trade, losing days included, on Telegram. There is a free blueprint for anyone who wants the capital protection material in one place, and an optional Kit for people who want the full method. Nothing here promises a profit, and nothing here is a signal service.
Getting money out belongs to Protect, because capital you cannot reach is not capital you own. How to protect your capital when gold gets volatile is the pillar this article sits under, how to verify forex account documents covers the paperwork that has to be finished before any withdrawal will clear, how to check a forex broker licence is the register check to run before the first deposit, and how to spot a gold trading scam deals with the wider pattern the IC3 report describes. More about who writes this is on the about page.
About the author. Raphael writes Black Gold Market. He works on the part of this business that happens before the entry, the level, the context, and the risk, and he takes an unusually dim view of any arrangement where money is easy to send and difficult to retrieve. Nothing in this article is a recommendation to trade, and no entry, stop or target discussed should be treated as a signal.
Disclaimer: This article is general educational content about withdrawal mechanics, account verification and fraud patterns in retail trading. It is not financial advice, not investment advice and not a recommendation to buy, sell or use any product, venue or firm. Regulatory wording is quoted from the sources linked in the text and may change, and rules vary by jurisdiction. Trading leveraged products carries a substantial risk of loss and most retail accounts lose money. Figures are illustrative calculations from stated assumptions, not predictions or performance claims.